

 Contact Us
 Other Insurance
Road Tax in Maharashtra
Date: Nov 17, 2026 - Last Modified Nov 17, 2026


Maharashtra, known for its diverse landscapes and major cities, has an extensive road network connecting urban centres, industrial areas and tourist destinations. The state government levies road tax in Maharashtra to support road infrastructure and related public services.
Owning a vehicle in Maharashtra involves more than choosing a model and completing registration. Road tax in Maharashtra varies by vehicle category, with private vehicles generally attracting a one-time tax and transport vehicles subject to periodic taxation. Understanding how factors such as vehicle value, fuel type, capacity and weight affect the tax can help buyers budget accurately without confusing it with registration charges or insurance.
What is Road Tax in Maharashtra
Road tax in Maharashtra is levied under the Maharashtra Motor Vehicles Tax Act, 1958 and the Maharashtra Motor Vehicles Tax Rules, 1959. It applies to vehicles used or kept for use in the state, with rates varying based on factors such as fuel type and vehicle category. Road tax is separate from registration fees, permits, road-safety cess and insurance, even when these charges appear together. Check the applicable official tax schedule for your vehicle before making the payment.
Who Needs to Pay Road Tax in Maharashtra
Liability generally depends on where and how the vehicle is registered or used. The main groups are:
- Owners registering a private two-wheeler, car or other non-transport vehicle in Maharashtra.
- Operators of taxis, buses, goods vehicles and other transport vehicles used in the state.
- Owners bringing an out-of-state vehicle to Maharashtra for more than one year, when assignment of a Maharashtra registration mark becomes necessary.
- Commercial operators using vehicles in Maharashtra under applicable permit and tax arrangements.
Exception: Motor vehicles used solely for agricultural operations on farms or farmland are exempt from road tax, excluding trailers drawn by motor vehicles.
How Road Tax Works in Maharashtra
Private vehicles commonly pay a one-time tax at first registration. Transport vehicles follow the period and basis assigned to their class, which can be annual or another prescribed interval. The liability should be determined based on the exact class schedule, not inferred from private-car rates.
Vehicle category | Payment basis | Frequency | When due |
Private motorcycle | Engine capacity and vehicle value | One-time | At first registration |
Private car | Fuel type and vehicle value | One-time | At first registration |
Passenger transport vehicle | Class and seating capacity | One-time or annual | As prescribed for the class |
Goods vehicle | Gross vehicle weight or unladen weight | One-time or annual | At registration or before the next tax period |
How Maharashtra Road Tax is Calculated
Begin with the official vehicle classification. Private motorcycles use engine capacity; private cars use fuel and value bands. Commercial vehicles use factors such as gross vehicle weight, seating and permit class. Age matters for migrated vehicles and refunds.
Use the vehicle cost recognised under the tax law and official schedule, not the total on-road amount containing insurance and registration charges.
Vehicle’s age, type, engine capacity, seating capacity, and fuel type
Identify individual or non-individual ownership and whether the vehicle is imported.
Apply any road-safety cess, exemption or concession separately where applicable.
Example: A ₹8 lakh private petrol car falls in the up-to-₹10 lakh band. At 11%, tax is ₹88,000 before separate fees or cess. The RTO assesses the vehicle based on the applicable tax rules, which determines the payable road tax in Maharashtra.
Road Tax Rates for Two-Wheelers in Maharashtra
The official private-vehicle schedule uses engine capacity for an individually owned motorcycle. This makes road tax in Maharashtra for 2 wheeler purchases different from a simple value-only slab.
Engine capacity | Tax rate | Applicable period |
Up to 99 cc | 10% of vehicle value | One-time |
100 cc to 299 cc | 11% of vehicle value | One-time |
300 cc and above | 12% of vehicle value | One-time |
Non-individual or imported motorcycle | 20% of vehicle value | One-time |
For road tax in Maharashtra bike estimates, confirm cubic capacity on the invoice. Battery vehicles are covered under the EV section.
Note: A minimum road tax of ₹1,500 applies to motorcycles in Maharashtra, even if the calculated tax based on the applicable percentage is lower. The final tax payable is subject to the prevailing Maharashtra Motor Vehicles Tax Act and applicable rules.
Road Tax Rates for Cars in Maharashtra
For an individually owned car, the official schedule separates petrol, diesel and CNG/LPG. The following road tax in Maharashtra for 4 wheeler table uses non-overlapping value bands.
Vehicle value | Petrol | Diesel | CNG or LPG | Period |
Up to ₹10 lakh | 11% | 13% | 7% | One-time |
Above ₹10 lakh and up to ₹20 lakh | 12% | 14% | 8% | One-time |
Above ₹20 lakh | 13% | 15% | 9% | One-time |
The road tax in Maharashtra car schedule places non-individual and imported petrol or diesel cars at 20%, subject to a ₹20 lakh maximum. Comparable CNG/LPG rates are 14%, 16% and 18%.
Road Tax for Commercial and Goods Vehicles in Maharashtra
Commercial rates are class-specific and based on capacity, seating or operation.
Commercial Goods Vehicle
Loading capacity or class | Tax rate | Frequency |
Delivery van: GVW up to 750 kg | ₹8,400 | One-time |
Delivery van: GVW 751-1,500 kg | ₹13,650 | One-time |
Delivery van: GVW 1,501-3,000 kg | ₹18,900 | One-time |
Delivery van: GVW 3,001-4,500 kg | ₹25,200 | One-time |
Medium/heavy goods: GVW 7,501-9,000 kg | ₹6,450 | Annual |
Medium/heavy goods: GVW 9,001-10,500 kg | ₹7,500 | Annual |
Passenger Vehicles
Passenger vehicle | Capacity or class | Tax rate | Frequency |
Motor cab | 3+1 to 6+1 seats | ₹3,850-₹7,150 | One-time |
Private service vehicle | Non-AC | ₹1,000 per seat | Annual |
Private service vehicle | AC | ₹2,000 per seat | Annual |
General contract carriage | 13+1 to 24+1 seats | ₹1,700 per seat | Annual |
General contract carriage | 25+1 seats and above | ₹1,900 per seat | Annual |
Road Tax for Vehicles Registered in Another State
A vehicle registered elsewhere and kept in Maharashtra for more than one year must obtain a Maharashtra registration mark. Required records include the original authority’s NOC, financier consent where applicable, RC, insurance and PUC. Forms vary by address change, ownership and category. The RTO assesses tax using the vehicle’s details and age. For a short stay, retain evidence of entry and home-state tax. Any refund of tax paid earlier is claimed from the previous state after re-registration.
EV, Hybrid and CNG Exemptions in Maharashtra
The Maharashtra Electric Vehicle Policy 2025 gives a complete motor-vehicle-tax exemption to electric vehicles sold and registered in the state during the policy period.
Vehicle type | Current treatment | Policy window or basis | Reference |
Battery electric vehicle | 100% motor-vehicle-tax exemption | 1 April 2025 to 31 March 2030 | Maharashtra EV Policy 2025 |
Hybrid vehicle | No blanket EV-policy exemption identified | Ordinary applicable schedule | State tax schedule |
CNG/LPG private car | Concessional rates of 7%, 8% or 9% | Current published value bands | State tax schedule |
Green Tax in Maharashtra
Under the Maharashtra Motor Vehicles (Taxation) Act, the state levies a green tax, also called Environmental Cess, to help mitigate pollution on older vehicles. For non-transport vehicles, it becomes payable after 15 years and covers the subsequent five-year period. Transport vehicles generally become liable for tax payment at 8 years, with separate provisions for CNG and LPG vehicles.
Vehicle age | Vehicle type | Green tax | When payable |
After 15 years | Non-transport two-wheeler | ₹2,000 | For each five-year period |
After 15 years | Other non-transport petrol vehicle | ₹3,000 | For each five-year period |
After 15 years | Other non-transport diesel vehicle | ₹3,500 | For each five-year period |
After 8 years | Non-CNG/LPG auto-rickshaw | ₹750 | For each five-year period |
After 8 years | Non-CNG/LPG tourist taxi or light goods vehicle | ₹2,500 | For each five-year period |
After 8 years | Other specified transport vehicles | 2.5% or 10% of annual tax by class | Annually |
How to Pay Maharashtra Road Tax Online
Keep the registration number and payment details ready before starting road tax Maharashtra online payment.
Open Parivahan Sewa and select Online Services, then ‘Vehicle Related Services’.
Choose ‘Maharashtra’ and the relevant RTO, then sign in or continue with the registration number as prompted.
Select Pay Vehicle Tax and review the vehicle particulars.
Check the tax period, amount and any arrears before confirming the transaction.
Pay by an available method and download the receipt.
Verify that the payment status has updated. If money was debited but the receipt was not generated, retain the transaction reference and contact the VAHAN helpdesk or jurisdictional RTO before paying again.
The state department routes vehicle services to VAHAN. Save the receipt as the record of road tax Maharashtra online payment.
How to Check Pending Road Tax Dues
The process to check pending road tax dues is quick and straightforward:
- Open VAHAN’s ‘Vehicle Related Services’ and choose the state and RTO.
- Enter the registration number and complete the authentication requested by the portal.
- Open the tax service or Know Your MV Tax view to see the due period, tax amount and recorded payment status.
If the vehicle class, tax period or earlier payment is wrong, do not overwrite the discrepancy with another payment. Take the RC, prior receipt and portal screenshot to the RTO or raise it with the VAHAN helpdesk.
How to Pay Maharashtra Road Tax Offline
If you do not want to opt for the online service of road tax payment in Maharashtra, here are the steps to pay road tax offline:
- Visit the RTO or taxation authority that has jurisdiction over the vehicle.
- Submit the applicable tax form with the RC, invoice or earlier tax receipt and supporting documents.
- Pay the assessed amount through the payment mode accepted at the counter and collect the stamped receipt.
Carry originals and photocopies. Counter or service charges, where applicable, are separate from tax; retain the receipt with the vehicle records.
Documents Required to Pay Maharashtra Road Tax
The exact checklist varies by transaction, but commonly required documents include:
- Registration Certificate; the number may suffice for an online lookup.
- Vehicle invoice or sale certificate for registration or value assessment.
- Identity and Maharashtra address proof for an RTO application.
- Previous tax receipt for periodic renewal or record correction.
- Valid motor insurance and PUC, necessary for the transaction.
- NOC, financier consent and prescribed forms for an out-of-state vehicle.
Commercial vehicles may also ask for permits or fitness documents.
Penalty for Late or Unpaid Road Tax in Maharashtra
Non-payment can create tax, interest and composition liability.
Rule 19 calculates composition for each month or part-month at 4% of tax in default when voluntarily reported and 8% otherwise. The ordinary cap is the tax in default; for a specified repeat offence within two years, it can reach twice that amount.
Situation | Composition amount | Maximum |
Default voluntarily reported | 4% tax in default per month or part | Tax in default |
Default not voluntarily reported | 8% of tax in default per month or part | Tax in default |
Specified repeat offence within two years | Applicable monthly calculation | Twice the tax in default |
Section 12 treats unpaid tax and interest as arrears of land revenue, while section 12B permits seizure and detention until dues are paid. The RTO should calculate the live amount before payment.
Road Tax Refund and Transfer in Maharashtra
A refund may arise after permanent removal and re-registration elsewhere, or cancellation following scrapping. The taxation authority handles the claim; it is not an automatic VAHAN credit.
Obtain the NOC, complete re-registration in the destination state and retain proof of the new registration and tax paid there.
Submit Form DT to the Maharashtra taxation authority with the taxation certificate or receipt, RC records, proof of removal and bank details requested by the office.
For scrapping, add the cancellation record and insurer certificate or other evidence that the vehicle is beyond repair.
Follow up with the RTO; processing time depends on verification and the applicable statutory refund scale.
A transfer of ownership within Maharashtra does not by itself recreate the one-time tax already paid, although transfer fees and any outstanding dues remain payable. The road tax Maharashtra car refund is determined under section 9 and the applicable schedule, not by a flat percentage quoted online.
How Maharashtra Road Tax Compares with Neighbouring States
State comparisons need care because tax bases differ. These are headline treatments for new private vehicles, not model quotations.
State | Two-wheeler rate | Car rate | Basis |
Maharashtra | 10%-12% individual; 20% non-individual/imported | Petrol 11%-13%; diesel 13%-15%; CNG/LPG 7%-9% | Engine capacity and vehicle value |
Gujarat | Use state calculator for current lump-sum tax | Use state calculator for current lump-sum tax | Sale price, vehicle and ownership inputs |
Goa | Rate varies by notified value band | Rate varies by notified value band | Cost and vehicle class under Goa tax law |
Madhya Pradesh | Rate varies by vehicle value/class | Rate varies by vehicle value/class | Schedule under MP taxation law |
Maharashtra is granular because fuel and capacity change the percentage. Compare the same value, fuel and ownership type rather than relying on the lowest headline rate.
Road Tax vs Car Insurance: What is the Difference
Road tax authorises use of a vehicle on public roads while insurance manages specified financial risks. They are separate from legal and financial obligations.
Road tax and car insurance serve different purposes.
Here is a detailed explanation:
Feature | Road tax | Motor insurance |
Paid to | State government | Insurer |
Purpose | Vehicle taxation and lawful road use | Third-party liability and, if selected, own-damage protection |
Mandatory status | Applicable under state tax law | Third-party cover compulsory under section 146 of the Motor Vehicles Act, 1988 |
Payment pattern | One-time or periodic by vehicle class | Policy term and renewal cycle |
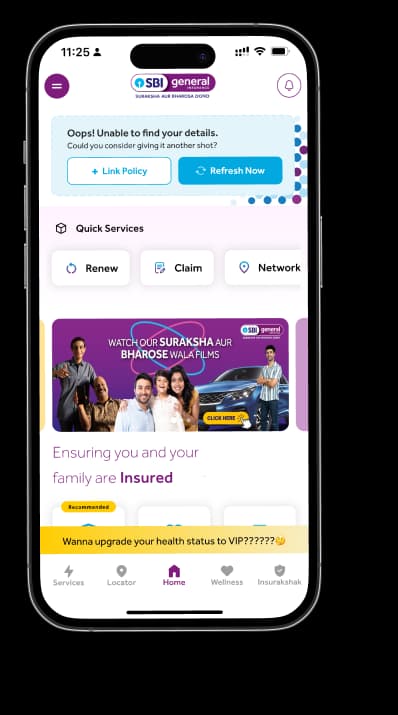
SBI General Insurance offers a range of motor insurance solutions, including car insurance and two-wheeler insurance, to help vehicle owners protect themselves against covered risks. With access to 9,000+ network garages and 24×7 customer support through the SBI General Insurance mobile app, policyholders can seek assistance when needed.
Note: These products do not replace road tax, registration or permit obligations; they address insurance cover separately.
Conclusion
The liability for road tax in Maharashtra depends on vehicle, fuel, ownership and use. Start with the official classification, then separate tax from cess, fees and insurance.
Before paying or registering a migrated vehicle, verify the current rate and any active exemption with the Maharashtra Motor Vehicle Department or jurisdictional RTO.
Frequently Asked Questions
How is road tax calculated in Maharashtra?
Private motorcycles use engine capacity and value; private cars use fuel and value bands. Commercial vehicles follow weight, seating, permit or class-based schedules. Ownership, import status, age and exemptions may also affect assessment.
Is road tax a one-time payment in Maharashtra?
Private motorcycles and cars generally pay once at registration. Transport vehicles may pay periodically by class. Older vehicles may separately attract environmental tax at the prescribed threshold.
How do I pay road tax online in Maharashtra?
Use VAHAN Vehicle Related Services, select Maharashtra and the RTO, open Pay Vehicle Tax, verify dues, pay and download the receipt. Retain the transaction reference if no receipt appears.
What is the penalty for not paying road tax?
Rule 19 uses 4% per month or part when default is voluntarily reported and 8% otherwise, subject to caps. Unpaid tax may also lead to recovery and vehicle detention.
Are electric vehicles exempt from road tax in Maharashtra?
Eligible EVs sold and registered from 1 April 2025 to 31 March 2030 receive full motor-vehicle-tax exemption. Hybrids lack that blanket benefit; CNG/LPG cars use lower scheduled rates.
What is green tax?
Environmental tax applies after 15 years for non-transport vehicles. Certain non-CNG/LPG transport vehicles enter after eight years; specified CNG/LPG transport vehicles are treated from 15 years.
Can I get a road tax refund if I move states?
A refund may be claimed after permanent removal and re-registration, subject to section 9 and its schedule. Submit Form DT, tax records and proof of the new registration to the taxation authority.
Do I pay road tax again if I move to Maharashtra?
After more than one year, obtain a Maharashtra registration mark and pay tax assessed by the RTO. Claim any available refund from the previous state after re-registration.
This blog is intended solely for educational and informational purposes. Content reflects data at time of publication and may not accurately reflect current premiums, terms, or regulations. Readers are encouraged to confirm the accuracy and relevance of the data before making any significant decisions. SBI General Insurance disclaims responsibility for any errors or consequences arising from the use of outdated information provided herein. For more details, please refer to the policy wordings and prospectus before concluding the sales. *Add-ons are subject to payment of additional premium.
Access and manage all your Insurance Needs in one place, right at your Fingertips.
4/5*
Access and manage all your Insurance Needs in one place, right at your Fingertips.
Vision
Our vision is to become the most trusted general insurer for a transforming India.
Mission
Our mission is to provide simple and innovative general insurance solutions, be responsive to our customers' needs and build a sustainable business for the future.
We're socially active!