

 Contact Us
 Other Insurance
Does Car Insurance Cover Diwali Firecracker Damage? Cover and Claim Checks
Date: Nov 19, 2026 - Last Modified Nov 19, 2026


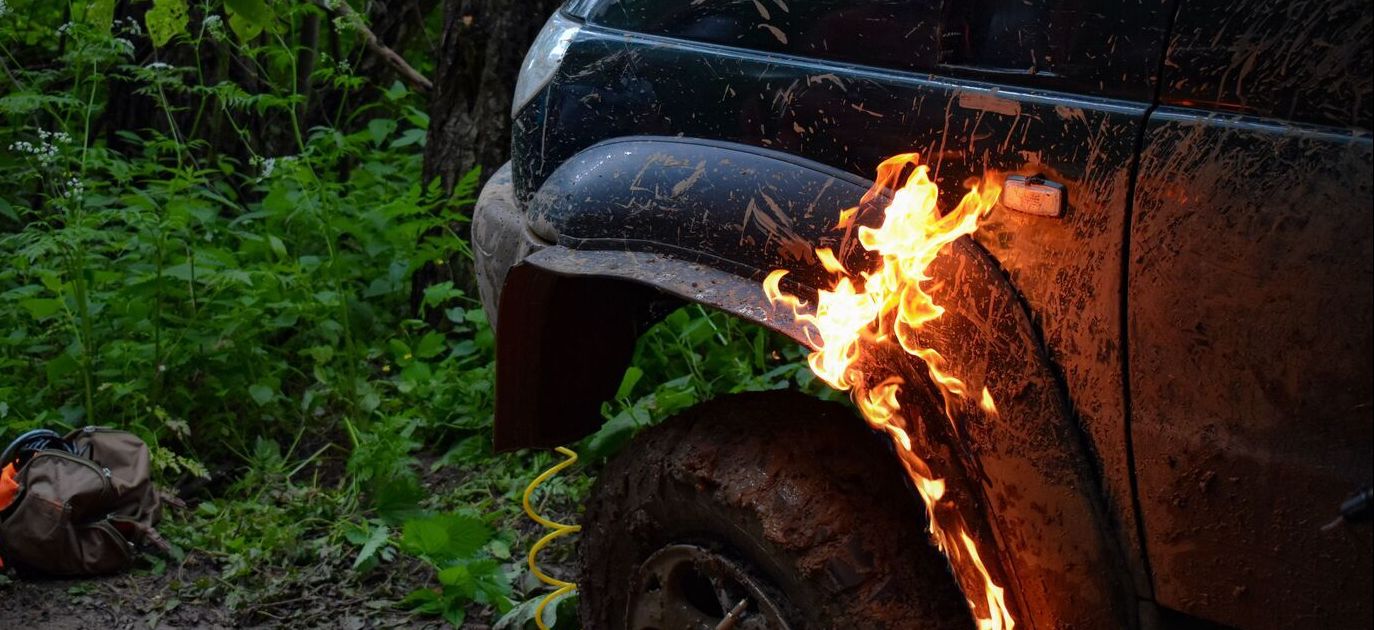
After an evening of Diwali celebrations, a car owner finds a scorch mark near the bonnet. Crowded streets and frequent fireworks increase the risk of vehicle damage. The first question is whether car insurance covers such damage.
The short answer is that it can. Does car insurance cover fire damage from a stray spark? This comes down to the cause of the damage, the cover you chose and the terms of your policy. This guide explains the available cover types and the steps involved in making a claim.
Is Firecracker Damage Covered by Car Insurance
Firecrackers are not named as a specific cause in a motor policy. Instead, the damage is assessed against the causes the policy does cover, which typically include fire, explosion, self-ignition and accidental external means.
Does car insurance cover fireworks damage? In practice, a comprehensive policy can respond when a stray spark sets off a fire, and cover also extends to damage caused by malicious acts. The key is the cause of the loss, not the firework itself.
*Disclaimer: Coverage depends on the cause of loss, the cover selected and the policy wording. Please refer to the policy wording of SBI General Insurance.
Which Policy Type Covers What
Whether fire damage is covered depends on the type of cover you hold. Understanding how car insurance works helps you choose the right cover for risks like fire and explosion. Own damage insurance is the part that pays for loss or damage to your own car, and it can sit inside a package policy or be bought as a stand-alone cover alongside a valid third-party policy. A third-party policy, on its own, only covers your liability to others. Here is how the three options compare for a fire or firecracker loss and whether they cover damage to the insured car itself.
Own damage insurance is the part that pays for loss or damage to your own car, and it can sit inside a package policy or be bought as a stand-alone cover alongside a valid third-party policy. A third-party policy, on its own, only covers your liability to others. Here is how the three options compare for a fire or firecracker loss: is the cover for loss or damage to the insured car itself.
Cover type | Third-party liability | Damage to your own car (including fire) | When it fits |
| Third-party only | Covered | Not covered | Meeting the legal minimum |
| Standalone own damage | Needs a separate third-party policy | Covered | Adding own-car protection when valid third-party cover already exists |
| Comprehensive / package | Covered | Covered | Both protections in one policy |
*Disclaimer: Features and coverage can change. Please refer to the policy wording and sales brochure.
Fire, Sparks, Explosion and Short Circuits: Why the Cause Matters
Fire damage is not covered in every case, because the cause decides the outcome. Fire, self-ignition, explosion and lightning are generally covered causes under a comprehensive policy. A surveyor verifies documents and assesses each loss against policy terms.
A common question: Is fire covered in car insurance when it starts in the engine bay, in other words, does car insurance cover engine fire? An actual fire or self-ignition is a covered cause, but a mechanical or electrical breakdown on its own is not payable. The distinction matters: the fire is covered, the underlying fault that caused it may not be.
What about electrical fires? Does car insurance cover electrical fires? Damage from an actual fire is assessed under the fire cause. The Battery Guard add-on* covers repair or replacement expenses arising from unexpected power surges while charging the battery, water ingress or short circuits that cause loss or damage to specified components, including the ISG (Integrated Starter Motor), ECM (Engine Control Module), CPU (Computer Central Processor), Li-Ion Battery, Inverter, CPP (Clutch Pedal Position) and Neutral Position Switches, Transmission Range Sensor, Combination Meter, Brake Stroke Sensor, DC Converter, Power Inverter, Charge Port, Onboard Charger and Thermal System. Claims must be reported within 30 days of the loss, unless otherwise agreed by the insurer.
What Shapes Claim Approval
Admissibility depends on the documents submitted, the cause of loss and the policy terms, conditions and coverage. A surveyor verifies the documents and assesses the loss against the policy wording, including applicable exclusions.
Standard exclusions still apply. A claim can be affected if the car was driven by someone without a valid licence or under the influence of alcohol or drugs, or if the loss is traced to an unauthorised modification the insurer was not told about.
A fitted CNG or LPG kit needs its own attention. Own damage cover for the CNG/LPG kit requires an endorsement, subject to its declared value in the policy schedule. Fittings outside the manufacturer’s listed price must be specified in the schedule and require an additional premium. A compulsory deductible applies to each insured event, along with any voluntary deductible opted for by the insured. Depreciation is deducted from the value of replaced parts at applicable rates.
What to Do Immediately After Discovering Damage
Does car insurance cover fireworks damage if it is reported late? The policy requires immediate written notice of any accidental loss or damage, so a fire damage car insurance claim begins with prompt intimation.
- Stay at a safe distance until any fire or smoke has cleared.
- Record the details with photographs of the damage and surroundings.
- Give notice to SBI General Insurance at 1800 102 1111 or customer.care@sbigeneral.in.
- Submit the requested documents, such as the driving licence and FIR where applicable.
- Avoid driving the damaged car until necessary repairs have been completed to prevent further damage.
*Disclaimer: Contact details and claim requirements can change. Please check sbigeneral.in for current details.
How Survey, Repair and Total-Loss Settlement Work
SBI General Insurance appoints a surveyor within 24 hours of claim intimation. The survey report is submitted within 15 days of the surveyor’s appointment. The claim is settled or rejected within 7 days of receiving the last document.
Repairs can be cashless at a network garage or settled through reimbursement. Cashless repairs are settled directly with the garage. The Insured Declared Value (IDV) is the sum insured for the car. A car becomes a constructive total loss when the aggregate cost of retrieval and/or repair exceeds 75% of its IDV. Settlement is based on the IDV minus the value of the wreck, subject to the applicable policy terms and deductions.
How to Reduce Firecracker-Related Risks When Parking
The policy wording requires the insured to take reasonable steps to safeguard and maintain the car. Parking away from areas where people burst crackers can lower the chance of sparks reaching the car. Keeping policy details handy also helps when intimating a claim.
Key takeaways:
Coverage depends on the cause of loss and the cover selected
Own damage or comprehensive cover applies to the insured car
Prompt intimation supports a smooth claim assessment
Surveyor findings and policy wording guide the final decision
Own Damage Cover with SBI General Insurance
SBI General Insurance offers comprehensive car insurance that combines third-party liability with own damage cover. Car owners who already hold third-party cover can choose their own damage car insurance as a stand-alone cover.
Add-ons* such as Depreciation Reimbursement and Engine Guard extend the base cover for an additional premium. The motor claim process explains cashless and reimbursement claims. Intimation is accepted on the toll-free number, WhatsApp and the SBI General Insurance mobile app. Two-wheeler owners can also read the bike fire safety guide on fire causes and prevention.
*Disclaimer: Features, coverage and add-ons* may change. Add-ons* are optional and need an additional premium. Please refer to the policy wording and sales brochure.
FAQs
Does car insurance cover damage from firecrackers during Diwali?
It can, depending on the cause of damage and the cover selected. The Private Car Insurance Policy - Package lists fire, explosion and accidental external means as covered causes. Third-party-only cover does not apply to damage to the owner’s own car.
Does car insurance cover fire damage from a short circuit?
Fire is a listed cause, while electrical breakdown itself is not payable. The surveyor’s assessment helps establish the cause and applicable policy coverage, so the outcome depends on the findings and policy wording.
Does third-party car insurance cover fire damage to my own car?
No. Third-party cover addresses liability towards others, so own car fire damage needs own damage or comprehensive cover.
Will my No Claim Bonus be affected by a fire claim?
The No Claim Bonus (NCB) is an own damage renewal benefit for claim-free years. The Protection of NCB add-on* helps retain NCB after a claim, subject to its conditions.
What happens if my car is declared a total loss after a fire?
Settlement is based on the IDV less the wreck value, subject to deductibles and policy terms. Depreciation Reimbursement does not apply to total loss claims.
*Disclaimer: Answers reflect policy wording at the time of writing. Please refer to the current policy wording of SBI General Insurance. Add-ons* are subject to additional premiums and the terms and conditions of the policy.
This blog is intended solely for educational and informational purposes. Content reflects data at time of publication and may not accurately reflect current premiums, terms, or regulations. Readers are encouraged to confirm the accuracy and relevance of the data before making any significant decisions. SBI General Insurance disclaims responsibility for any errors or consequences arising from the use of outdated information provided herein. For more details, please refer to the policy wordings and prospectus before concluding the sales. *Add-ons are subject to payment of additional premium.
Access and manage all your Insurance Needs in one place, right at your Fingertips.
4/5*
Access and manage all your Insurance Needs in one place, right at your Fingertips.
Vision
Our vision is to become the most trusted general insurer for a transforming India.
Mission
Our mission is to provide simple and innovative general insurance solutions, be responsive to our customers' needs and build a sustainable business for the future.
We're socially active!