 Download App



Bike Insurance Policy Online
Bike Insurance Policy Online



#As on May 2026.
%As on December 2025.
*Premium may differ as per coverages and other factor opted for at time of quotation. Premium mentioned above refers to the minimum annual premium for Third Party premium for Two Wheelers.
Bike Insurance
Two-wheeler insurance, also known as bike insurance, is a type of insurance policy designed to provide financial protection for motorcycles, scooters and other registered two-wheelers against unforeseen events. It covers a range of risks, such as accidents, third-party losses, theft or natural disasters, depending on your chosen coverage.
In India, under the Motor Vehicles Act, 1988, as may be amended from time to time, it is mandatory to have a third-party insurance plan to drive on Indian roads. Failing to comply with this legal obligation may result in penalties or even the suspension of the vehicle’s registration.
With SBI General’s two-wheeler insurance, you can choose coverage suited to your needs, with benefits such as cashless repair facilities across 1,799+ two-wheeler garages, ₹15 lakh personal accident cover and access to a range of add-ons, subject to the terms and conditions of the policy.
Bike Insurance
What is Bike Insurance?
Bike insurance is a type of insurance policy where the insurer provides coverage against financial losses arising from accidents, theft, natural disasters and third-party liabilities involving your two-wheeler.
Under the Motor Vehicles Act, 1988, having at least Third-Party (TP) insurance is mandatory for two-wheelers used on public roads. You can opt for a TP-only policy to meet the legal requirement or choose broader protection through a Comprehensive or Standalone Own Damage policy.
The premium and coverage depend on factors such as the type of policy, vehicle specifications, IDV, location and applicable discounts. For example, the base annual TP premium starts at ₹538 for two-wheelers with engine capacity up to 75 cc, as prescribed under the applicable Motor Vehicles (Third Party Insurance Base Premium and Liability) Rules.
What is Bike Insurance?
At a Glance
- Third-party insurance is mandatory under the Motor Vehicles Act, 1988.
- TP premiums start at ₹538/year for two-wheelers up to 75 cc.
- Personal Accident Cover can provide up to ₹15 lakh, subject to policy terms.
- NCB can help reduce eligible Own Damage premiums.
- Insured Declared Value (IDV) is the insured value of your two-wheeler for Own Damage cover.
- Premiums vary based on IDV, vehicle details, coverage and add-ons.
At a Glance
Key Features of SBI General Bike Insurance Policy
| Key Features | Benefits |
|---|---|
| Bike Insurance Premium | Starts at ₹538* |
| Cashless Garages | 1,799+ network garages # |
| No Claim Bonus | Up to 50% |
| Third-Party Damage Cover | Covers injury/death of any third party or damage to any third-party property |
| Personal Accident Cover | ₹15 lakh for individual owners |
| Own Damage Cover | Covers fire, explosion, accidental damage, natural calamities, theft, riots, strikes, malicious activity, etc. |
| Add-Ons$ | Over 9 add-on covers available |
| Hassle-free Buying/Renewing Process | Buy or renew your policy through the website or SBI General Insurance mobile app |
Types of Bike Insurance Plans Available in India
Ride with confidence!
What is Covered Under Bike Insurance?
Third-Party Liabilities/ Losses
This includes damage to other individuals’ vehicles or property, as well as injuries or deaths caused by your two-wheeler.
Personal Accident Cover
This includes a sum insured of ₹15 lakh for individual owners of the vehicle and a sum insured of up to ₹1 lakh for pillion riders.
Man-Made Disasters
A comprehensive plan will cover damage to your bike caused by incidents such as riots, malicious acts, and terrorist activities.
Natural Disasters
Coverage includes damage to the insured bike due to cyclones, floods, storms, earthquakes, etc.
Fire Disasters
Coverage includes damage to your two-wheeler caused by an explosion, fire, lightning or self-ignition.
Vehicle Stolen/ Total Loss
This includes financial loss resulting from the theft of a vehicle or total loss.
Loss or Damage Whilst in Transit
Coverage for the insured two-wheeler while it is being transported by road, rail, inland waterway, lift, elevator or air.
What’s Not Covered Under Bike Insurance?
What’s Not Covered Under Bike Insurance?
 Damage to your bike caused by mechanical or electrical issues.
- Damage caused if the rider is under the influence of alcohol or drugs.
- Repair or replacement of bike parts due to normal wear and tear.
- Damage to your vehicle while the policy was not active.
- Damage/injuries caused while riding the bike without a helmet.
- Accidents caused by unlawful activity, such as racing.
- Incidents occurring outside India’s geographical boundaries.
- Damage or rider injury due to wars, mutiny or nuclear risk.
Zero Depreciation Cover for Bike Insurance
Zero Depreciation Cover, also known as Depreciation Reimbursement, can reimburse the depreciation applicable to parts of the insured vehicle that are approved for replacement under a partial loss claim. This cover is available on payment of an additional premium, subject to the terms and conditions of the policy.
What does Zero Depreciation Cover include?
- Reimbursement of applicable depreciation on replaced parts approved under a partial loss claim.
- No reimbursement is provided for Total Loss, Constructive Total Loss or Theft claims under this cover.
- The cover does not include the compulsory deductible or any voluntary deductible selected under the policy.
Example of Zero Depreciation Cover
Suppose your bike meets with an accident and a covered partial-loss claim requires a damaged part to be replaced.
- Cost of the replacement part: ₹10,000
- Applicable depreciation: ₹2,000
- Without Depreciation Reimbursement add-on, the applicable depreciation may be deducted from the claim amount.
- With Depreciation Reimbursement add-on, the ₹2,000 applicable depreciation on the approved replacement part can be reimbursed, subject to the policy terms.
Types of Two-Wheelers Covered by SBI General Bike Insurance
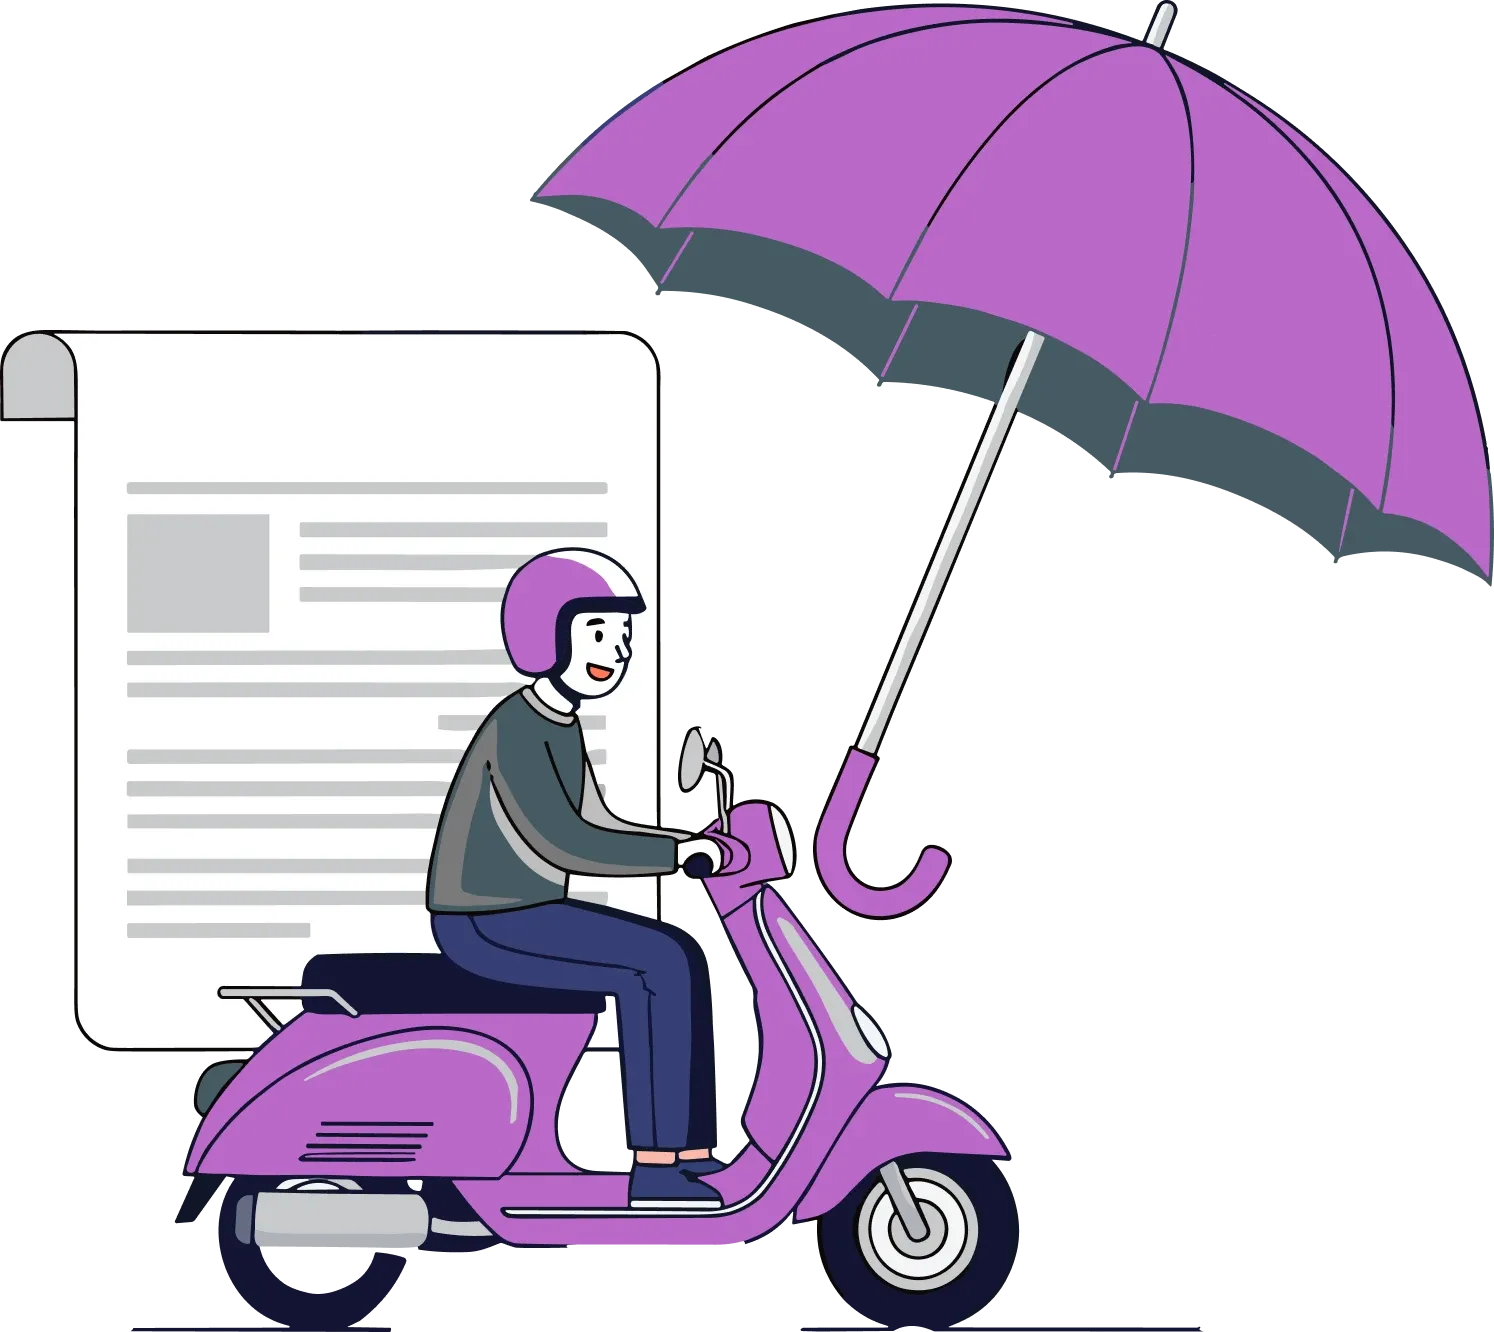
Geared Bikes
Geared bikes include standard motorcycles with manual gears, such as those from Royal Enfield, Honda and Bajaj, that are typically designed for higher power and longer rides. These bikes are commonly used for daily commuting as well as highway travel.
Sports Bikes & Superbikes
Sports bikes and high-performance motorcycles from brands such as KTM and BMW may require protection against risks associated with higher-value vehicles.
Non-Geared Scooters
Bike insurance covers gearless two-wheelers such as scooters from brands such as Honda and TVS that are easy to ride and ideal for city commutes. This category is suitable for riders looking for convenience, comfort and fuel efficiency.
Electric Bikes
Electric bikes are powered by batteries and are designed for eco-friendly commuting. Insurance coverage may extend to risks such as accidental damage, theft and other unforeseen incidents.
Mopeds
Mopeds are low-powered two-wheelers typically used for short-distance travel. Compact and economical, mopeds are also covered under the policy for essential protection on everyday rides.
GST on Bike Insurance Premiums
| Particulars | GST Before Reform | GST After Reform |
|---|---|---|
| Comprehensive Bike Insurance | 18% | 18% |
| Own-Damage Bike Insurance | 18% | 18% |
| Third-Party Liability Insurance | 18% | 18% |
| Add-Ons | 18% | 18% |
*Tax benefits are subject to applicable laws and may change.
GST on Bikes
The GST rate applicable to the vehicle itself is separate from the GST applicable to insurance services:
| Vehicle Type | GST |
|---|---|
| Motorcycles up to 350 cc | 18% |
| Motorcycles above 350 cc | 40% |
| Electric two-wheelers | 5% |
GST on the vehicle can affect its underlying price, which can in turn influence the IDV used for Own Damage insurance; the IDV is then one of the factors considered when determining the Own Damage premium.
Bike Insurance for Electric Two-Wheelers
Electric two-wheelers require specialised protection and SBI General Insurance offers coverage tailored to their unique needs.
You can enhance coverage with add-ons such as zero depreciation, roadside assistance, and NCB protection. With flexible policy options and easy online access, SBI General Insurance helps EV owners ride with confidence while embracing a cleaner and more sustainable mode of transport.
| Vehicle Type | Annual Third-Party Coverage Premium | Five-Year Single Premium |
|---|---|---|
| Not exceeding 3 KW | ₹457 | ₹2,466 |
| Exceeding 3 KW but not exceeding 7 KW | ₹607 | ₹3,273 |
| Exceeding 7 KW but not exceeding 16 KW | ₹1,161 | ₹6,260 |
| Exceeding 16 KW | ₹2,383 | ₹12,849 |
*Disclaimer: EV coverage is subject to vehicle eligibility and the policy’s terms, conditions, exclusions and applicable limits.
NCB in Bike Insurance
What is NCB?
When is NCB Lost?
NCB Transfer Benefit
How Does NCB Work?
| Policy Age | NCB Percentage |
|---|---|
| 1 year of no claim | 20% |
| 2 consecutive years of no claim | 25% |
| 3 consecutive years of no claim | 35% |
| 4 consecutive years of no claim | 45% |
| 5 consecutive years of no claim | 50% |
What is NCB?
How Does NCB Work?
| Policy Age | NCB Percentage |
|---|---|
| 1 year of no claim | 20% |
| 2 consecutive years of no claim | 25% |
| 3 consecutive years of no claim | 35% |
| 4 consecutive years of no claim | 45% |
| 5 consecutive years of no claim | 50% |
When is NCB Lost?
NCB Transfer Benefit
How is Two-Wheeler Insurance Premium Calculated?
| Premium Component | Illustrative Amount |
|---|---|
| Own Damage premium | ₹1,200 |
| Third-Party premium | ₹800 |
| Personal Accident cover | ₹100 |
| Add-Ons | ₹500 |
| NCB Discount | - ₹240 |
| Premium (illustrative) | ₹2,360 |
Bike Insurance Premiums
| Two-Wheeler Category | 1-year TP premium | 5-year TP premium* |
|---|---|---|
| Up to 75 cc | ₹538 | ₹2,901 |
| >75 cc to 150 cc | ₹714 | ₹3,851 |
| >150 cc to 350 cc | ₹1,366 | ₹7,365 |
| Above 350 cc | ₹2,804 | ₹15,117 |
| Electric Bike up to 3 kW | ₹457 | ₹2,466 |
| >3 kW to 7 kW | ₹607 | ₹3,273 |
| >7 kW to 16 kW | ₹1,161 | ₹6,260 |
| above 16 kW | ₹2,383 | ₹12,849 |
Who Should Buy Comprehensive Bike Insurance?
New Bike Owners:
Consider comprehensive protection with Return to Invoice cover to manage the shortfall between the claim amount and vehicle’s purchase price.
Daily Commuters:
Engine Guard cover can provide additional protection against specified engine-related risks.
Long-Distance Riders:
Road-Side Assistance Cover can provide support in case of a breakdown or other covered roadside emergencies.
Sports Bike Owners:
Tyre & Rim Guard Cover can provide additional protection against specified tyre and rim damage.
Delivery & Gig Riders:
Inconvenience Allowance can provide financial support for eligible periods when the insured vehicle is under repair following a covered loss.
How to Buy a Bike Insurance Policy Online?
- 1.Go to SBI General Insurance Website → Products → Two-Wheeler Insurance Policy.
- 2.Input your bike registration number, mobile number and pin code, and click ‘Proceed’.
- 3.Evaluate the covers based on features and add-ons. Choose a suitable motor insurance policy for your vehicle.
- 4.Complete your KYC verification.
- 5.Input the required information, such as proposer details, EIA (e-insurance account), and nominee details.
- 6.Make the payment online and get your policy right away in your inbox.
Buying Insurance for a New Bike
If your new bike does not yet have a registration number, you may need to provide the relevant vehicle details available at the time of purchase and update the registration details as required.
Switching from Another Insurer
If you are moving from another insurer, keep your existing policy details and NCB information handy. Compare the coverage, IDV, deductibles and add-ons before purchasing the new policy.
Documents Required to Buy Two-Wheeler Insurance
| Category | Details |
|---|---|
| Identity Proof | Aadhaar Card, PAN Card, Passport, or Driving Licence |
| Address Proof | Aadhaar Card, Passport, Voter ID, or utility bills |
| Vehicle Registration Certificate (RC) | Required vehicle ownership document; invoice in case the vehicle is brand new |
| Previous Insurance Policy | Applicable if you have an existing or past insurance policy |
| Additional Details (If needed) | May vary based on requirement |
| Invoice / Purchase Details | Proof of vehicle purchase |
| Inspection Details | Required in case of expired insurance policies, or if you want additional coverage beyond your previous year’s policy |
Why Should You Get a Bike Insurance Policy Online?
Get Instant Quotes
Quick Issuance
Minimal Documentation
Payment Reminders
Planning a road-trip soon? Here’s a biker’s checklist!
How to File a Bike Insurance Claim Online?
- Call us on 1800 102 1111 or email customer.care@sbigeneral.in and inform us about your claim with your policy details.
- Once your claim is registered, our customer support executive will provide you with a Claim Reference Number.
- You will be required to submit the relevant documents, including your Driving License, RC Copy, and Policy FIR Copy, as per the Policy terms and conditions.
- We will arrange for an inspection. It will be conducted within 24 hours if a claim is reported on a working day, or the next working day if the claim is reported on a Sunday or a public holiday.
- On cashless facility confirmation, the vehicle can be repaired at a preferred network garage, and payment can be made directly to the garage.
- You will only be required to pay the deductible as mentioned in the policy and the depreciation value, salvage, etc., as the surveyor has informed you.
You can also raise and track a claim through the SBI General Insurance Mobile App. Download the app today for an easy, hassle-free claim experience!
Understand why having bike insurance is mandatory in India and protect your ride!
Essential Documents for Filing a Bike Insurance Claim
| Category | Documents |
|---|---|
| Basic Documents |
Duly filled and signed claim form RC copy of the insured vehicle Original estimate of loss (repair estimate) Original repair invoice and payment receipt |
| For Accidental Claims |
Copy of Registration Book (Please furnish original for verification) Copy of Motor Driving License of the person driving the vehicle at the time of accident (Please furnish original for verification) Police Panchnama/FIR (In case of Third-Party property damage / Death / Body Injury / Fire / Malicious Damage Claims) Estimate for repairs from repairer where vehicle is to be repaired Repair Bills/Invoices after the job is completed Payment receipts after the job is completed KYC/AML for losses above ₹1 lakh |
| For Theft Claims |
Original Policy document Original Registration Book / Certificate, Permit, Fitness Certificate, Tax Certificate & Load Challan. Police Panchnama / FIR Final Investigation Report from the magistrate’s court under section 173 Cr.P.C / Non-Traceable Report. All the sets of Keys / Service Booklet / Warranty Card / Original purchase invoice Acknowledged copy of letter addressed to RTO intimating theft and informing "NON-USE" of vehicle Form 28, 29 and 30 signed by the insured and Form 35 signed by the Financer, as the case may be, undated and blank Letter of Undertaking, Subrogation & Discharge Voucher Consent towards agreed claim settlement value from yourself and Financier. NOC from the Financier if claim is to be settled in your favour |
Why Bike Insurance Claims Get Rejected and How to Avoid It
Policy Has Expired
Damage is Not Covered
Incomplete or Incorrect Information
Driving Without a Valid Licence
Driving Under the Influence
Late Claim Intimation
False or Fraudulent Claims
How to Renew a Bike Insurance Policy?
- Visit the official SBI General Insurance website → Renewals → Motor Policy.
- Enter Policy Number and bike’s RC number.
- Enter your policy’s expiry date and whether or not you have filed a claim under it.
- Choose the renewal policy suited for your plan and pick the cover you want to add. (If you have not filed any claim, you can avail of perks associated with the No Claim Bonus feature.)
- Proceed to make the premium payment.
- After payment completion, your renewed insurance policy will be available for download as well as sent to the registered email address.
How to Renew an Expired Bike Insurance Policy?
How to Renew an Expired Bike Insurance Policy?
- Visit the official SBI General Insurance website → Renewals → Motor Policy.
- Enter Policy Number and bike’s RC number.
- Choose the renewal policy suited for your plan and pick the cover you want to add. (If you have not filed any claim, you can avail of perks associated with the No Claim Bonus feature.)
- Proceed to make the premium payment.
- After payment completion, your renewed insurance policy will be available for download as well as sent to the registered email address.
Buying or Renewing Insurance for an Old or Second-Hand Bike
Bike Insurance Terms You Should Know
Compulsory Deductible
Voluntary Deductible
Total Loss
Constructive Total Loss
Break-in Policy
Grace Period
Consumables
Cashless Settlement
Personal Accident (PA) Cover
Reviews & Ratings

Rishab Singh
Health Insurance
★★★★★

Himanshu
Car Insurance
★★★★★
Sulabha Ravikiran
Health Insurance
★★★★★
FAQs About Bike Insurance Policy
You can make an online payment for bike insurance through net banking, mobile wallet, debit card or credit card.
The premium payable for two-wheeler insurance will vary from one policyholder to another. Other factors include geographical location, the model and make of the bike, the capacity of the engine, the year of manufacture and voluntary deductible.
At least third-party insurance is mandatory in India, regardless of your bike’s age.
If you sell your bike, you can transfer your bike insurance policy to the new owner.
It meets legal requirements but offers limited coverage. A comprehensive plan provides broader protection.
Two Wheeler Insurance Policy
Two Wheeler Insurance Policy – Package
IRDAN144RP0006V02201112
Bundled Two-Wheeler Insurance Policy
IRDAN144RP0007V02201819
SBI General Insurance and SBI are separate legal entities and SBI is working as Corporate Agent of the company for sourcing of insurance products. Number of network hospitals would differ based on the TPA servicing your policy.
Lower Premiums apply only to select RTOs and specific vehicle makes/models. Offers may vary based on location and availability.
*T&C Apply